
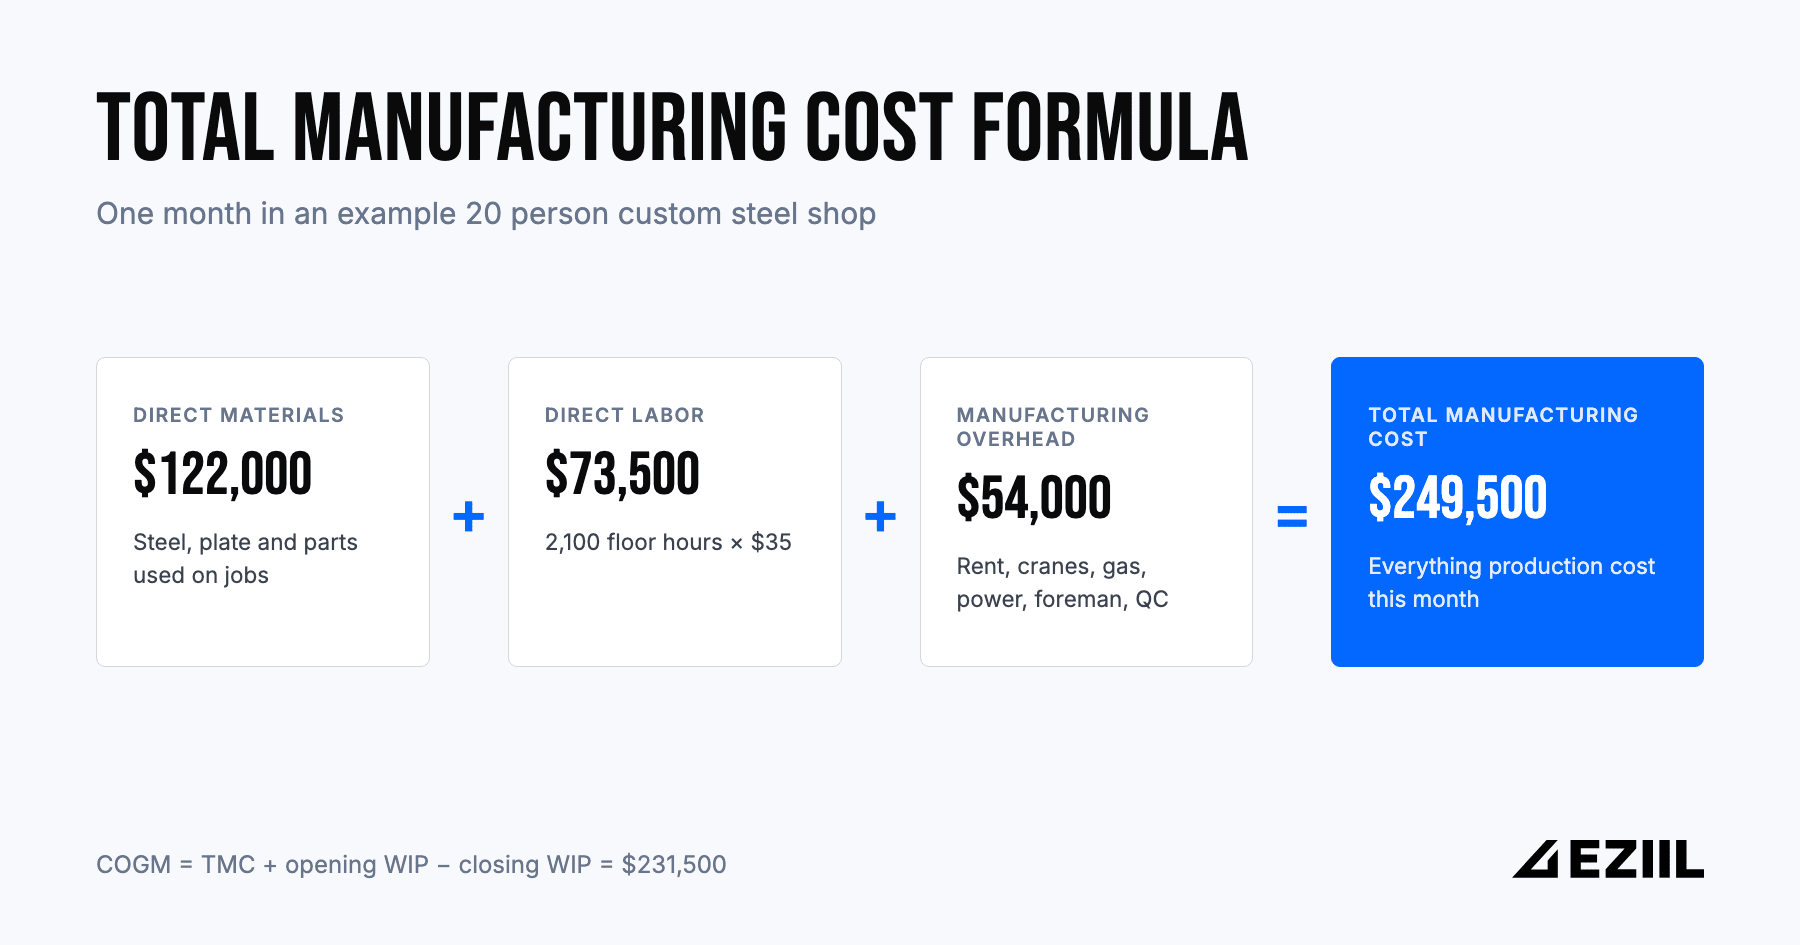
The total manufacturing cost formula is direct materials + direct labor + manufacturing overhead, added up for one period, usually a month. That sum is your total manufacturing cost (TMC). Add the opening work in progress, subtract the closing work in progress, and you have the cost of goods manufactured (COGM).
This guide is for owners and managers of small custom fabrication and job shops who get these numbers from their accountant and want to know what they do and don’t tell them. It works through both formulas with one month of numbers from an example 20 person steel shop, then shows how to get from the monthly total to the cost of a single job. That last step is where EZIIL, our own product, comes in.
What is the total manufacturing cost formula?
Total manufacturing cost = direct materials used + direct labor + manufacturing overhead, for one period. It counts every production cost the shop incurred in that period, whether the work was finished or not.
| Component | What it means | In a fabrication shop |
|---|---|---|
| Direct materials | Materials that become part of the product | Steel sections, plate, tube, bolts, bought-in parts used on jobs |
| Direct labor | Wages for the people who make the product | Fitters, welders, cutters and painters, for hours worked on jobs |
| Manufacturing overhead | Every other production cost | Shop rent, cranes, gas and consumables, power, the foreman, QC, equipment depreciation |
| Total manufacturing cost | Direct materials + direct labor + manufacturing overhead | Everything production cost the shop this month |
Scroll sideways to see all columns.
The period matters. TMC is a monthly (or yearly) figure for the whole shop. It doesn’t belong to any one job, which is where it starts to fall short for a job shop. More on that below.
The three inputs in a fabrication shop
A fabrication shop’s total manufacturing cost comes from three inputs: the steel and parts used on jobs, the hours fitters and welders spend on jobs, and everything else it takes to run the shop floor.
Direct materials
Direct materials used = opening raw material inventory + purchases − closing raw material inventory. That is the steel, plate and parts that actually left the rack during the month, not what you bought.
Consumables such as wire, discs and gas are usually treated as overhead, because few shops trace them to a job. Material only becomes a job’s cost once someone books it to that job, which is why the moments steel moves through your shop decide your job cost.
Direct labor
Direct labor is the hours your fitters, welders and cutters spend on jobs, times what those hours cost you. Use the loaded rate, not the hourly wage. For example, the US median wage for welders, cutters, solderers and brazers was $51,000 a year in May 2024, about $24.50 an hour. Benefits make up 30 percent of what private employers spend on compensation. So an hour that pays $24.50 costs the shop about $35.
Only hours on jobs count. Sweeping the bay, unloading a delivery or waiting for drawings is not direct labor, even when the timesheet says it was.
Manufacturing overhead
The manufacturing overhead formula is simple: manufacturing overhead = all production costs − direct materials − direct labor. In other words, everything it takes to run the shop floor that you can’t pin to one job. AccountingTools lists the same kind of items: factory rent, supervision, utilities, depreciation and supplies.
In a fab shop, manufacturing overhead usually includes:
- Shop rent or mortgage interest, and property tax on the building
- Overhead cranes, forklifts, and their maintenance
- Shielding gas, wire, grinding discs and other consumables not booked to a job
- Electricity for welders, saws and lasers
- Depreciation on machines and equipment
- Foreman, yard, QC and maintenance wages
- Insurance on the shop and equipment
Office rent, sales commissions, the bookkeeper and marketing are not manufacturing overhead. They are selling and administrative costs, and they stay out of TMC. Our glossary has more on overhead in steel fabrication.
Prime cost and conversion cost
Two related formulas often come up next to TMC:
- Prime cost = direct materials + direct labor
- Conversion cost = direct labor + manufacturing overhead
Prime cost is what goes straight into the product. Conversion cost is what it takes to turn raw steel into a finished assembly.
How to calculate total manufacturing cost: a worked example
Here is how to calculate total manufacturing cost for one month in an example custom steel shop with 20 people, 14 of them on the floor. The numbers are illustrative; swap in your own from the month’s books.
- Direct materials. The shop started the month with $42,000 of steel and parts on the rack, bought $118,000 more, and ended with $38,000. Direct materials used: $42,000 + $118,000 − $38,000 = $122,000.
- Direct labor. The floor booked 2,100 hours to jobs at a loaded rate of $35. Direct labor: 2,100 × $35 = $73,500.
- Manufacturing overhead. Rent $14,000, foreman, yard and QC wages $16,500, gas and shop consumables $6,200, power $4,800, equipment depreciation $7,500, maintenance $2,300, insurance $2,700. Overhead: $54,000.
- Total manufacturing cost. $122,000 + $73,500 + $54,000 = $249,500.
| One month, example shop | Amount |
|---|---|
| Raw material, start of month | $42,000 |
| + Steel, plate and parts purchased | $118,000 |
| − Raw material, end of month | $38,000 |
| Direct materials used | $122,000 |
| Direct labor2,100 hours × $35 | $73,500 |
| Manufacturing overheadRent, foreman, yard and QC, gas, power, depreciation, maintenance, insurance | $54,000 |
| Total manufacturing cost | $249,500 |
| + Work in progress, start of month | $86,000 |
| − Work in progress, end of month | $104,000 |
| Cost of goods manufactured | $231,500 |
Scroll sideways to see all columns. Illustrative numbers for an example shop. Swap in your own from the month's books.
What is the COGM formula?
Cost of goods manufactured = total manufacturing cost + opening work in progress − closing work in progress. COGM is the cost of the work you actually finished in the period.
In the example: $249,500 + $86,000 − $104,000 = $231,500.
To find cost of goods manufactured for your own shop:
- Calculate total manufacturing cost for the period, as above.
- Add the value of work in progress at the start of the period.
- Subtract the value of work in progress at the end of the period.
In a fabrication shop, work in progress (WIP) is often the biggest and least certain number in the schedule. Made to order jobs run for weeks or months, so at every month end there are half welded frames and painted but unshipped platforms on the floor. Someone has to put a value on them, and that is usually an estimate of how far each job has got. AccountingTools sets out the same schedule if your accountant wants the textbook version.
Total manufacturing cost vs COGM vs COGS
TMC is what you spent on production this period, COGM is the cost of what you finished, and COGS is the cost of what you sold. They are three steps of the same calculation.
| Formula | What it answers | Where you see it | |
|---|---|---|---|
| TMCTotal manufacturing cost | Direct materials + direct labor + manufacturing overhead | What did production cost us this month? | Internal cost reports |
| COGMCost of goods manufactured | TMC + opening WIP − closing WIP | What did the work we finished cost? | Schedule of cost of goods manufactured |
| COGSCost of goods sold | COGM + opening finished goods − closing finished goods | What did the work we sold cost? | Income statement |
Scroll sideways to see all columns.
In a make to order fab shop, finished goods inventory is usually close to zero, because jobs ship when they are done. In the example both are $0, so COGS equals COGM at $231,500.
So is total manufacturing cost the same as COGS? Only when work in progress and finished goods don’t change during the period. In a shop with long jobs they rarely stay still.
Why the monthly total won’t tell you which jobs made money
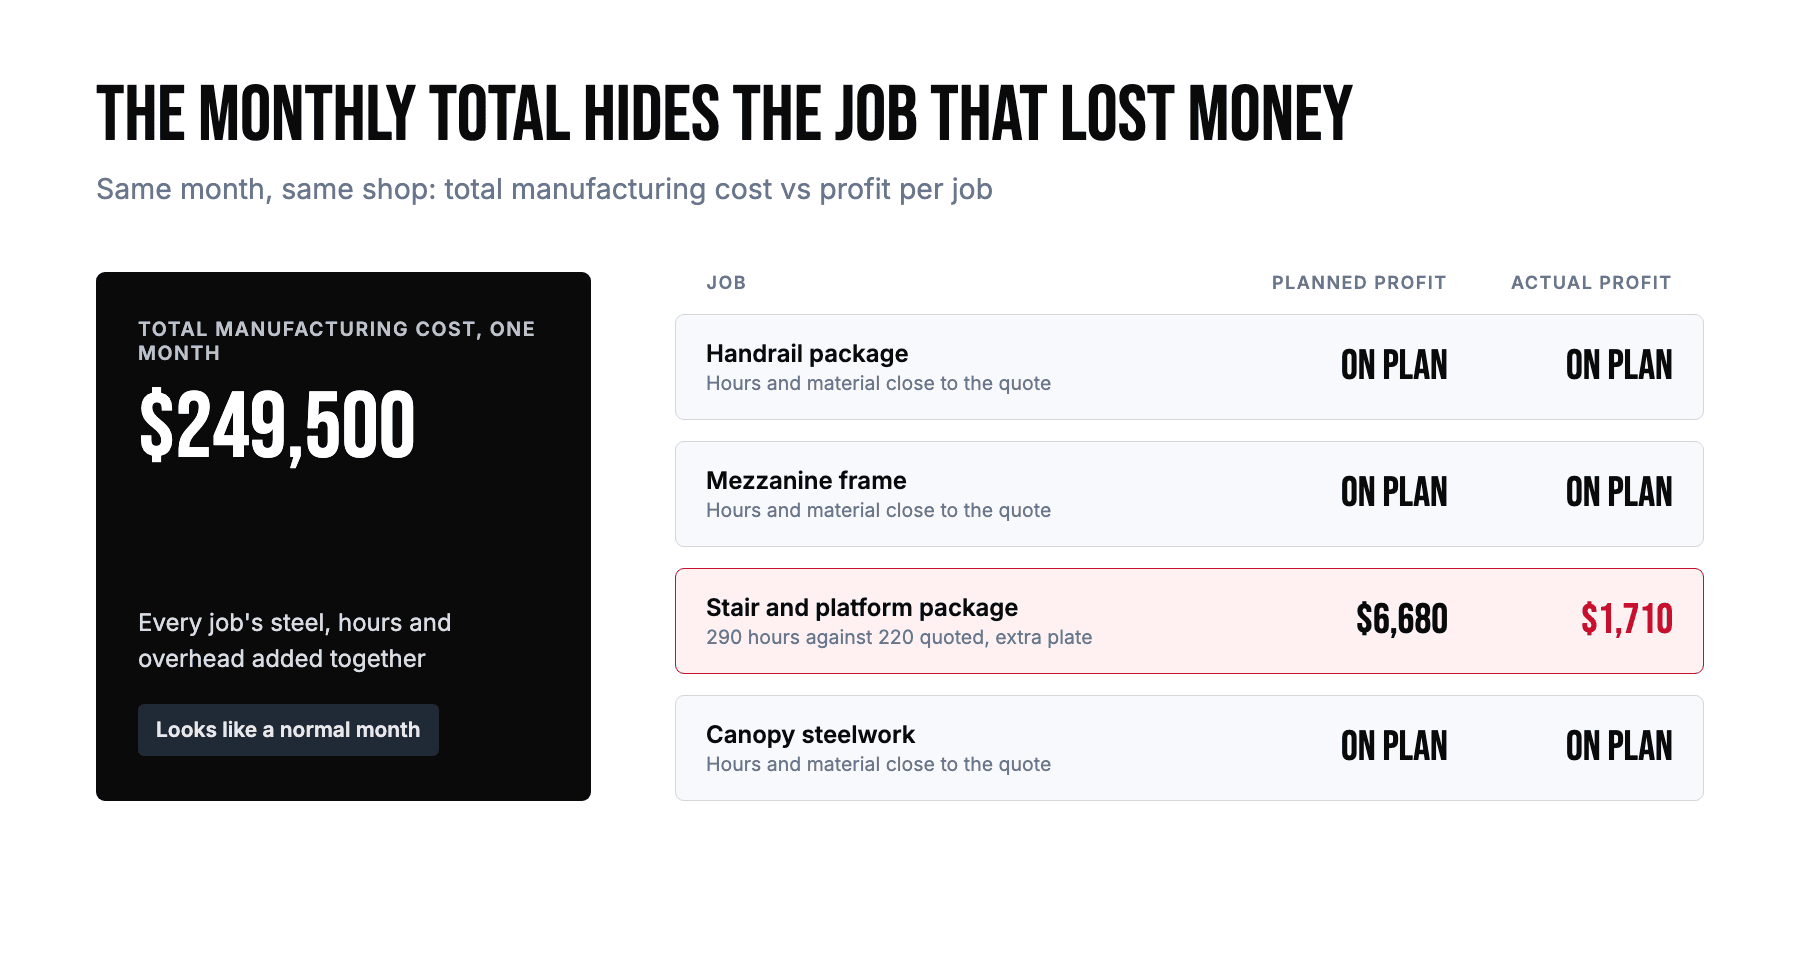
TMC is a number for the whole shop for a whole month, so a job that lost money hides inside it. The formula adds every job together; it can’t tell you which one went wrong.
There are three reasons it falls short for a job shop:
- It averages. Ten jobs that made money and one that lost money produce a perfectly normal looking month.
- WIP is a judgment call. On long jobs, the closing WIP value moves cost between months, so one month can look better than it was and the next worse.
- Overhead is spread evenly. In the books, a job that used the overhead crane for three days carries the same share of overhead as one that didn’t.
We hear this in our demo calls. The assistant plant manager of a US laser job shop put it plainly: he can quote a part and know what to charge, but when a part needs two extra hours of grinding, a job that should have made $100 loses $50, and nothing shows it. Others put it more simply: they want to know whether they are making any money on jobs.
From the monthly total to the cost of one job
Job cost = material booked to the job + hours recorded on the job × your cost per hour. It uses the same inputs as TMC, collected per job instead of per month.
The cost per hour comes from the same books. In the example, direct labor plus overhead is $127,500 for 2,100 floor hours, or about $61 per hour. How you set that rate, and whether to split it by machine or department, is a topic of its own: work it out with our free fabrication cost calculator and shop rate guide.
Take one job from the same month, a stair and platform package sold for $31,500:
| Stair and platform package | Quoted | Actual |
|---|---|---|
| Material | $11,400 | $12,100 (extra plate after a drawing change) |
| Hours | 220 | 290 (fit-up rework and grinding) |
| Labor and overhead at $61 per hour | $13,420 | $17,690 |
| Job cost | $24,820 | $29,790 |
| Profit on $31,500 | $6,680 | $1,710 |
Scroll sideways to see all columns.
The job made about a quarter of what was planned, and the month’s TMC of $249,500 looked normal. Without the job view, the next stair package gets quoted the same way.
What has to be true for job cost to be right
Job cost is only as good as the hours and material behind it. Four things make the difference:
- Hours recorded per job and operation while the work happens. A weekly timesheet written from memory puts yard time and helping a colleague on whatever job was open. We explain the three ways this goes wrong in why your job costing is wrong.
- Off-job time kept separate. Cleaning, training, waiting for drawings and rework are real costs, but they belong in overhead or on the job that caused them, not spread over whatever was on the timesheet.
- Material booked to the job when it is issued. That includes the extra plate after a drawing change, not just what the BOM said.
- Quoted vs actual checked while the job is still open. Finding the overrun after the invoice goes out tells you what went wrong. Finding it in week two lets you do something about it.
How EZIIL shows job cost while the job runs
EZIIL is production management software for custom metal fabricators and job shops. It doesn’t replace your accountant’s TMC and COGM; those still come from the books. It gives you the per job view the monthly formula can’t:
- Time per job and operation, from the floor. Workers start and stop a timer per operation and per assembly in the mobile app, on their phone or a shared tablet, signed in with a password or an RFID tag.
- Off-job time in its own place. Cleaning, training, waiting for drawings and defect repair go to support activities, on a project or off every job, so that time never lands on the wrong job.
- Hours checked every morning. In Working Time Confirmation, the office reviews yesterday’s reported time per worker and confirms it in one pass. Confirmed hours feed progress, the payroll export and the cost reports.
- Hours turned into cost. Set an hourly rate per operation in production settings, and confirmed hours show what the job has cost so far.
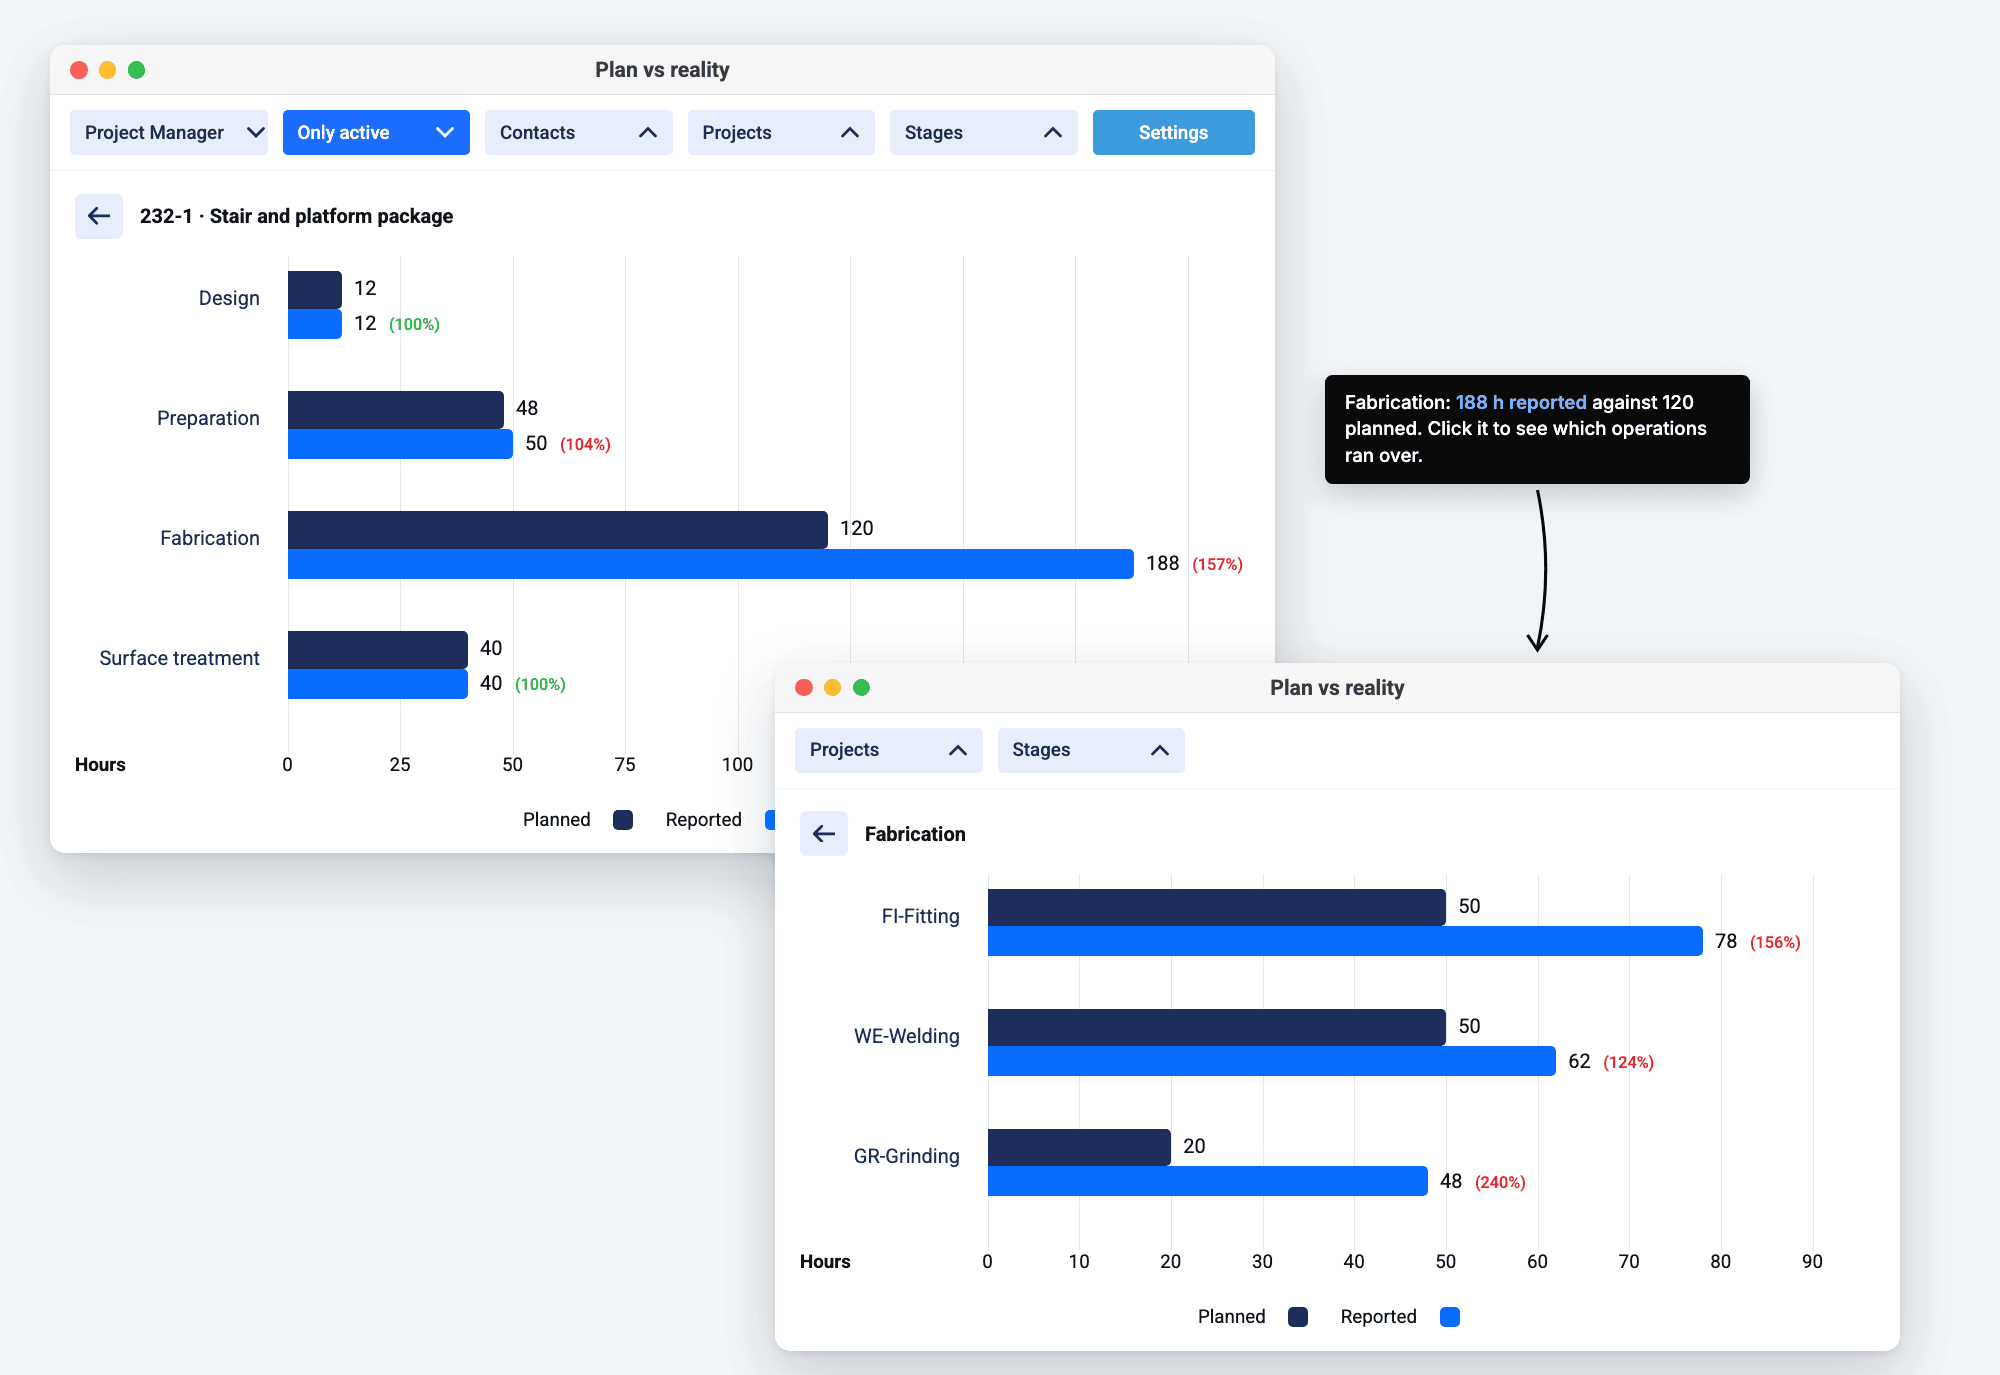
- Planned vs actual. The Plan vs reality report shows planned hours against reported hours for each project, down to the operation, and who reported the time on which day, so an overrun like the stair package above shows up while the job is still on the floor.
- Material on the job. With the bill of materials (BOM) and inventory modules, the Material Cost tool shows the material actually booked to each project, in money.
EZIIL connects with accounting software, including Xero, QuickBooks, Microsoft Dynamics and Merit, so invoices and the books stay where they are. EZIIL Starter covers planning, time reporting and labor cost from $140 a month for up to 15 users, flat, with no per user fees (prices as of November 2026).
APS Group, a Perth industrial fabricator running 20+ projects at a time on EZIIL Starter, describes the result. Syed Raza Hashimi, their planner and QA/QC manager: “Now we can see exactly what the workers are doing in the workshop and how many hours they are spending on each process. This has given us tighter control of active jobs, better-informed estimating and concrete profit/loss insights per job.”
To see how it works in a shop like yours, take a free tour of EZIIL or read more about job costing software for manufacturing. If you are comparing tools, we also cover the best job costing software for metal fabricators.
Frequently asked questions
Is total manufacturing cost the same as COGS?
No. Total manufacturing cost is everything spent on production in a period. COGS is the cost of the work sold in that period, after adjusting for changes in work in progress and finished goods. The two are equal only when neither inventory changes.
Does total manufacturing cost include selling and administrative costs?
No. TMC includes only direct materials, direct labor and manufacturing overhead. Office rent, sales, marketing and bookkeeping are selling and administrative costs and are reported separately.
How do you calculate cost of goods manufactured?
Take total manufacturing cost for the period, add the work in progress at the start, and subtract the work in progress at the end. In the example above: $249,500 + $86,000 − $104,000 = $231,500.
How often should a fab shop calculate total manufacturing cost?
Monthly, alongside the books, is enough for TMC and COGM. Job cost needs a shorter cycle: weekly at least, and daily on large jobs, so overruns show up while the job is still on the floor.
How do I find the cost of a single job?
Add the material booked to the job to the hours recorded on it, multiplied by your cost per hour. Our fabrication cost calculator walks you through it.
TMC for the month, job cost for each job
TMC and COGM are the accountant’s view of the month, and every shop needs them. They just can’t tell you which job made money. Keep the monthly formula, and add a per job view so the next underpriced job shows up while it is still on the floor.